All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
Social Security Fairness Act of 2023 (HR 82) – This bill, with 330 bipartisan sponsors and a similar bill in the Senate, was introduced by Rep. Garret Graves (R-LA) on Jan. 9, 2023. It passed in the House on Nov. 12 of this year and is likely to pass in the Senate before the year’s end. The purpose of the bill is to eliminate the government pension offset that reduces Social Security benefits for individuals who receive other benefits, such as a pension from a state or local government. In the private sector, this would have a similar effect to withholding Social Security from people who have a 401(k). The bill would also repeal provisions that reduce Social Security benefits for spouses and widows/ers who receive their own government pensions. The provisions of the bill would be retroactive to the beginning of 2024.
BOLIVAR Act (HR 825) – This legislation prohibits the head of an executive agency to enter into a contract for the procurement of goods or services with any person that has business operations with the Maduro regime in Venezuela. The act was introduced on Feb. 2, 2023, by Rep. Michael Waltz (R-OH). It passed in the House on Nov. 18, and its fate currently lies with the Senate.
Vote by Mail Tracking Act (HR 5658) – This bill would require mail-in ballots to use the Postal Service barcode and an Official Election Mail logo. It passed in the House on Nov. 18 and is under consideration in the Senate. The bill was introduced by Rep. Katie Porter (D-CA) on Sept. 21, 2023.
Find and Protect Foster Youth Act (S 1146) – This act was introduced on March 30, 2023, by Sen. John Cornyn (R-TX). It would amend a provision of the Social Security Act to require the Department of Health and Human Services to eliminate obstacles to identifying and responding to reports of missing foster care children. Furthermore, it would assist in the assessment and screening of children who are at risk of becoming victims of sex trafficking, as well as identify best practices for effective interventions. The bipartisan bill passed in the House on Nov. 18 and is currently in the Senate.
Billion Dollar Boondoggle Act of 2023 (S 1228) – This bill was introduced by Sen. Joni Ernst (R-IA) on April 25, 2023. The bill would require the director of the Office of Management and Budget to submit an annual report to Congress detailing projects that are over budget and behind schedule. This is a bipartisan bill that has passed in both the Senate and the House, but on July 22, the House made changes and sent it back to the Senate, where it currently resides.
Rural Broadband Protection Act of 2024 (S 275) – Introduced by Sen. Shelley Moore Capito (R-WV) on Feb. 7, 2023, this bill would require the Federal Communications Commission (FCC) to vet applicants for funding of affordable broadband deployment in high-cost areas (including rural communities). The FCC would mandate a process, including a detailed proposal with technical capabilities to provide competitive awards for implementing the broadband network services. The FCC would then assess proposals in line with well-established technical standards. The bill passed the Senate on Sept. 25 and is currently with the House.
Alan F Burke CPA
Making Pensions Equitable, Protecting Foster Kids, Mail-in Votes and Tracking Government Spending
December 1, 2024 · Blog, Congress at Work
⏱ 3 min read
All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.
Social Security Fairness Act of 2023 (HR 82) – This bill, with 330 bipartisan sponsors and a similar bill in the Senate, was introduced by Rep. Garret Graves (R-LA) on Jan. 9, 2023. It passed in the House on Nov. 12 of this year and is likely to pass in the Senate before the year’s end. The purpose of the bill is to eliminate the government pension offset that reduces Social Security benefits for individuals who receive other benefits, such as a pension from a state or local government. In the private sector, this would have a similar effect to withholding Social Security from people who have a 401(k). The bill would also repeal provisions that reduce Social Security benefits for spouses and widows/ers who receive their own government pensions. The provisions of the bill would be retroactive to the beginning of 2024.
BOLIVAR Act (HR 825) – This legislation prohibits the head of an executive agency to enter into a contract for the procurement of goods or services with any person that has business operations with the Maduro regime in Venezuela. The act was introduced on Feb. 2, 2023, by Rep. Michael Waltz (R-OH). It passed in the House on Nov. 18, and its fate currently lies with the Senate.
Vote by Mail Tracking Act (HR 5658) – This bill would require mail-in ballots to use the Postal Service barcode and an Official Election Mail logo. It passed in the House on Nov. 18 and is under consideration in the Senate. The bill was introduced by Rep. Katie Porter (D-CA) on Sept. 21, 2023.
Find and Protect Foster Youth Act (S 1146) – This act was introduced on March 30, 2023, by Sen. John Cornyn (R-TX). It would amend a provision of the Social Security Act to require the Department of Health and Human Services to eliminate obstacles to identifying and responding to reports of missing foster care children. Furthermore, it would assist in the assessment and screening of children who are at risk of becoming victims of sex trafficking, as well as identify best practices for effective interventions. The bipartisan bill passed in the House on Nov. 18 and is currently in the Senate.
Billion Dollar Boondoggle Act of 2023 (S 1228) – This bill was introduced by Sen. Joni Ernst (R-IA) on April 25, 2023. The bill would require the director of the Office of Management and Budget to submit an annual report to Congress detailing projects that are over budget and behind schedule. This is a bipartisan bill that has passed in both the Senate and the House, but on July 22, the House made changes and sent it back to the Senate, where it currently resides.
Rural Broadband Protection Act of 2024 (S 275) – Introduced by Sen. Shelley Moore Capito (R-WV) on Feb. 7, 2023, this bill would require the Federal Communications Commission (FCC) to vet applicants for funding of affordable broadband deployment in high-cost areas (including rural communities). The FCC would mandate a process, including a detailed proposal with technical capabilities to provide competitive awards for implementing the broadband network services. The FCC would then assess proposals in line with well-established technical standards. The bill passed the Senate on Sept. 25 and is currently with the House.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
No matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.
Break-Even Analysis
This formula analyzes fixed costs versus the profitability a business earns for every extra item it creates and sells.
Businesses that have smaller thresholds to meet their fixed costs to realize profitability have an easier break-even point to meet and exceed. Once the fixed costs threshold is satisfied and sales revenue outpaces variable costs, a business will know when it hits the break-even point.
Break Even Point (BEP) = Total Fixed Costs/(Price Per Unit – Variable Cost Per Unit)
This takes the total fixed costs divided by the price per individual unit minus each unit’s variable cost.
Examples of fixed costs are rent, taxes, insurance and wages. Examples of variable costs are raw materials, production supplies, utilities and packaging.
Another way to determine a company’s break-even point is as follows:
Contribution Margin = Item Price – Variable Cost Per Unit
This is illustrated by: $55 = ($85 – $30)
The item’s priced at $85, with a variable cost of $30, the contribution margin is $55 of how much revenue a company earns to pay for the remaining fixed costs.
Cash Ratio Formula
The cash ratio formula offers one way to look at a company’s liquidity position by comparing a company’s cash and cash equivalents to its current liabilities or debts due within the next 12 months. It shows how well positioned a business is (or is not) able to pay debts due within 12 months, and to satisfy the near-term obligations of its long-term debt.
It’s an important ratio that lenders look at when evaluating a company’s loan application. Instead of including assets such as accounts receivables, it factors in a business’ ability to take care of its financial obligations. It’s thought of as being a more real world look at how financially stable a business is.
This is defined as all income minus the cost of goods sold (COGS). COGS is comprised of expenses attributable to the creation of products, which include input materials and salaries for workers to produce such goods. However, it excludes expenses for taxes, overhead, debt, asset acquisitions, etc., among others. Another way to explain this calculation is to ask how much a business retains as profit once production costs are accounted for.
It’s calculated as follows: Gross Profit Margin = [(Net Sales – Cost of Goods Sold)/(New Sales)] x 100
Debt-to-Equity (D/E) Ratio
This is used to determine how much debt or financial leverage a company has on its books. It tells internal stakeholders and external parties what percentage of debt a company is using to operate compared to the business’ available operating reserves. This ratio contrasts a business’ complete financial obligations against its shareholder equity. Its primary use is to see how extensively it uses debt to operate.
It’s calculated as follows: Debt/Equity Ratio = Total Liabilities/Total Shareholders’ Equity.
While these calculations may seem straightforward, these are only a few examples of how businesses can calculate and analyze a company’s position – be it the owner, an employee or an outside lender or investor.
Alan F Burke CPA
Common Business Accounting Calculations
December 1, 2024 · Blog, General Business News
⏱ 3 min read
No matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.
Break-Even Analysis
This formula analyzes fixed costs versus the profitability a business earns for every extra item it creates and sells.
Businesses that have smaller thresholds to meet their fixed costs to realize profitability have an easier break-even point to meet and exceed. Once the fixed costs threshold is satisfied and sales revenue outpaces variable costs, a business will know when it hits the break-even point.
Break Even Point (BEP) = Total Fixed Costs/(Price Per Unit – Variable Cost Per Unit)
This takes the total fixed costs divided by the price per individual unit minus each unit’s variable cost.
Examples of fixed costs are rent, taxes, insurance and wages. Examples of variable costs are raw materials, production supplies, utilities and packaging.
Another way to determine a company’s break-even point is as follows:
Contribution Margin = Item Price – Variable Cost Per Unit
This is illustrated by: $55 = ($85 – $30)
The item’s priced at $85, with a variable cost of $30, the contribution margin is $55 of how much revenue a company earns to pay for the remaining fixed costs.
Cash Ratio Formula
The cash ratio formula offers one way to look at a company’s liquidity position by comparing a company’s cash and cash equivalents to its current liabilities or debts due within the next 12 months. It shows how well positioned a business is (or is not) able to pay debts due within 12 months, and to satisfy the near-term obligations of its long-term debt.
It’s an important ratio that lenders look at when evaluating a company’s loan application. Instead of including assets such as accounts receivables, it factors in a business’ ability to take care of its financial obligations. It’s thought of as being a more real world look at how financially stable a business is.
This is defined as all income minus the cost of goods sold (COGS). COGS is comprised of expenses attributable to the creation of products, which include input materials and salaries for workers to produce such goods. However, it excludes expenses for taxes, overhead, debt, asset acquisitions, etc., among others. Another way to explain this calculation is to ask how much a business retains as profit once production costs are accounted for.
It’s calculated as follows: Gross Profit Margin = [(Net Sales – Cost of Goods Sold)/(New Sales)] x 100
Debt-to-Equity (D/E) Ratio
This is used to determine how much debt or financial leverage a company has on its books. It tells internal stakeholders and external parties what percentage of debt a company is using to operate compared to the business’ available operating reserves. This ratio contrasts a business’ complete financial obligations against its shareholder equity. Its primary use is to see how extensively it uses debt to operate.
It’s calculated as follows: Debt/Equity Ratio = Total Liabilities/Total Shareholders’ Equity.
While these calculations may seem straightforward, these are only a few examples of how businesses can calculate and analyze a company’s position – be it the owner, an employee or an outside lender or investor.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
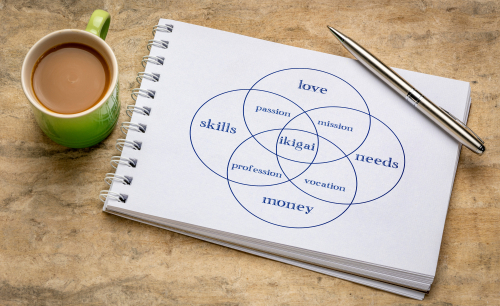
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Alan F Burke CPA
Pre-Retirement Planning Guide – Finding Purpose In Life
December 1, 2024 · Blog, Financial Planning
⏱ 5 min read
Step 7: Find Your Raison d’Etre
What do you consider to be your purpose in this world? Few people think about their life that way. In Japan, they call it your ikigai. In France, they refer to your raison d’etre. For Americans, that roughly translates to your purpose in life or your reason for being.
It’s easy to consider your family or even your career as your reason to live. But true embracement of the ikigai concept is more of a lifestyle, not a specific person, place or thing.
Your purpose may not even be something you’ve pursued in your adult life. Many of us follow the socially expected path: higher education, a good job, a rewarding career, marriage, home, and family. But those things are not everyone’s raison d’etre. They might wake up one morning thinking that once they’ve achieved all those goals, they will finally get the chance to do the one they’ve always wanted. What is that?
The older we get, the more we lose a spouse or life partner, siblings, or children – and those who retire no longer have work to feel fulfilled. As part of your retirement planning effort, consider life without any of those things. How would you bear it? If you outlive your career and loved ones, what would you do?
Note that your ikigai does not insulate you from bad things happening. Instead, it’s the thing you look forward to when the smoke clears: the light at the end of the tunnel. On balance, it’s the thing that helps get you through the pain and restores happiness. In fact, discovering your raison d’etre can help you better cope with stress and loss. People who pursue their ikigai tend to have better mental health, experience fewer chronic diseases, and are more likely to live longer.
Oftentimes ikigai is felt as part of a process. For example, the joy of mixing ingredients to prepare baked goods or a meal. Planting a garden. Rebuilding an engine. It can be the process of writing or painting or playing an instrument, but not necessarily finishing a novel or singing in public. It can be as simple as finding joy in daily activities, nurturing relationships or doing community service.
Another advantage to ikigai is that it can connect you with other people who share your passion, which can be very important as you grow older and more isolated. By leaning into your ikigai, you could expand your social network with connections that are meaningful and fulfilling.
For some people, their raison d’etre is spiritual. A belief and perhaps a greater connection to a higher being. They may wish to spend more time becoming involved in church activities, reading scripture that supports their religion, or even exploring other religions.
The Japanese culture believes that each individual has an inherent ikigai based on their personal values and beliefs. One way to think about it is as your philosophy on life. Since this step is a part of retirement planning, it is fortunate that you have lived long enough to have developed some philosophies on life.
For example, some people discover that family does not just consist of blood relatives. Instead, their concept of family is people who are there through good and bad times, who always show love and respect, who you can rely on. Those things might not always be true among family members who meet the traditional definition. This type of ikigai may help you recognize that the death of loved ones does not necessarily mean you lose your family. You can always build and add to your family (e.g., neighbors and friends, fostering children or pets, big brother/big sister programs).
How Do You Find Your Ikigai??
Many times, the hustle and bustle of life keeps us from finding our true purpose. We proceed as loyal soldiers down a path prescribed by society instead of pursuing things that may bring us greater happiness. There’s nothing wrong with a career and family, but there is likely something more that each of us can pursue that is personal and soul-enriching. Sometimes, you can discover your raison d’etre by exploring your passions, values, strengths, and skills. For example, ask yourself the following questions:
When I was a child, I loved doing…
If money didn’t matter, I would be…
If I believed I could not fail, I would…
I completely lose track of time when I am…
I am most happy with who I am when I…
I am really good at…
If I didn’t care what others thought, I would…
In my free time, I love to…
If I had only six months to live, I would spend my time…
If I were to die tomorrow, I would regret that I did not…
Consider hobbies or classes that you’ve always wanted to try or past experiences or achievements that gave you a sense of satisfaction and fulfillment. Recall where you have found inspiration in the past, and pinpoint what lies at the cross-section of doing what you love and doing what you’re good at.
Remember that your reason for living is more of a journey, not a destination. Finding your ikigai may take a lifetime to discover, so don’t be afraid to try out different pursuits. In fact, your reason for being may simply be to try new things.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.

 All bills not enacted by the end of the 118th congressional session on Jan. 3, 2025, will expire.



 No matter the type of business or industry, being able to analyze and deduce patterns is essential to discovering a business’ financial health. Here are four commonly used calculations to help internal and external stakeholders determine an organization’s ability to manage its finances.
 Step 7: Find Your Raison d’Etre