With the number of Amazon Prime member subscribers growing from 58 million in 2016 to 180 million in 2024, according to Statista, there’s a sustained recurring subscription model that one of America’s most successful retailers has increased more than 200 percent in eight years. Whether it’s a large company such as Amazon or a solopreneur beginning their recurring subscription services, it’s important to first distinguish between overall bookings and recurring revenue; and then to illustrate how businesses can measure these two types of revenue.
Dissecting Annual Recurring Revenue (ARR) and Bookings
Bookings are assurances of all anticipated earnings (recurring and one-off deals) because the business hasn’t satisfied the terms of the contracted services. Once it’s completed, the booking will turn into actual revenue. This factor is present in all sales deals, regardless of when revenue or cash will be transferred to the business from the customer. Non-recurring revenue includes training, special consulting projects, etc. (things that are one-off).
Annual Recurring Revenue (ARR) is a way to gauge recurring revenue a business projects to earn on a yearly basis. It’s quite common in eCommerce industries – be it subscriptions for food, software, etc. that are billed on a monthly or annual time frame.
How ARR Helps Businesses Analyze Operations
Businesses can determine demand trends, which help forecast recurring revenue. Lenders and investors can see how (in)efficient a company is with its marketing and sales efforts. It gives business owners and management the ability to determine customer retention and growth prospects while it provides internal and external users the ability to estimate a subscription’s worth. Additional insight businesses can gain from this metric include how much new customers add, how much renewals and upgrades impact ARR, and how churn and downgrades impact ARR.
How to Value a Company Using ARR
One common metric is Enterprise Value divided by ARR (EV/ARR), which is similar but important to distinguish from the EV/Revenue ratio. Since the ARR only factors in recurring revenue versus the EV/Revenue, which factors in all revenue regardless of the revenue recurring, the initial ratio provides a better assessment of the recurring revenue only. Assuming a company has an ARR multiple of 7 and its ARR is $15 million, the ARR has an enterprise value of $105 million.
Monthly Versus Yearly Recurring Revenue
While Monthly Recurring Revenue is not an entry on a business’s financial statements, it’s more of a key performance indicator (KPI). It’s not uncommon for companies to include it as part of their earnings releases. If a recurring subscription revenue is done monthly, it’s converted into Annual Recurring Revenue (ARR) as follows: MRR x 12 = ARR.
Recording Bookings
When a contract is signed, or an order is placed, it depends on how it’s handled. If the business receives cash prior to completing their monthly or yearly service expectation and say the contract is for $20,000 per month for 12 months, it would be recorded as follows:
Debit: Cash $240,000
Credit: Deferred Revenue $240,000
Since the contract has just been signed, but there’s been no product/service rendered, deferred or unearned, revenue has been created.
For every month that passes, the journal entry will progress as follows:
Debit: Deferred Revenue $20,000
Credit: Revenue $20,000
The deferred revenue account drops from $240,000 to $220,000, assuming the starting deferred revenue balance is even and there’s no deferred revenue.
The following month, the journal entries would be as follows:
Debit: Deferred Revenue $20,000
Credit: Revenue $20,000
This would occur every month until the end of the 12-month period.
Conclusion
When it comes to accounting for revenue, whether it’s booked, fulfilled by the company, or the payment received by the company, along with analyzing the time frame, it’s equally important to be familiar with the type of revenue it is for one to see how the company is performing.
Alan F Burke CPA
Dissecting Bookings and Annual Recurring Revenue
February 1, 2025 · Accounting News, Blog
⏱ 4 min read
With the number of Amazon Prime member subscribers growing from 58 million in 2016 to 180 million in 2024, according to Statista, there’s a sustained recurring subscription model that one of America’s most successful retailers has increased more than 200 percent in eight years. Whether it’s a large company such as Amazon or a solopreneur beginning their recurring subscription services, it’s important to first distinguish between overall bookings and recurring revenue; and then to illustrate how businesses can measure these two types of revenue.
Dissecting Annual Recurring Revenue (ARR) and Bookings
Bookings are assurances of all anticipated earnings (recurring and one-off deals) because the business hasn’t satisfied the terms of the contracted services. Once it’s completed, the booking will turn into actual revenue. This factor is present in all sales deals, regardless of when revenue or cash will be transferred to the business from the customer. Non-recurring revenue includes training, special consulting projects, etc. (things that are one-off).
Annual Recurring Revenue (ARR) is a way to gauge recurring revenue a business projects to earn on a yearly basis. It’s quite common in eCommerce industries – be it subscriptions for food, software, etc. that are billed on a monthly or annual time frame.
How ARR Helps Businesses Analyze Operations
Businesses can determine demand trends, which help forecast recurring revenue. Lenders and investors can see how (in)efficient a company is with its marketing and sales efforts. It gives business owners and management the ability to determine customer retention and growth prospects while it provides internal and external users the ability to estimate a subscription’s worth. Additional insight businesses can gain from this metric include how much new customers add, how much renewals and upgrades impact ARR, and how churn and downgrades impact ARR.
How to Value a Company Using ARR
One common metric is Enterprise Value divided by ARR (EV/ARR), which is similar but important to distinguish from the EV/Revenue ratio. Since the ARR only factors in recurring revenue versus the EV/Revenue, which factors in all revenue regardless of the revenue recurring, the initial ratio provides a better assessment of the recurring revenue only. Assuming a company has an ARR multiple of 7 and its ARR is $15 million, the ARR has an enterprise value of $105 million.
Monthly Versus Yearly Recurring Revenue
While Monthly Recurring Revenue is not an entry on a business’s financial statements, it’s more of a key performance indicator (KPI). It’s not uncommon for companies to include it as part of their earnings releases. If a recurring subscription revenue is done monthly, it’s converted into Annual Recurring Revenue (ARR) as follows: MRR x 12 = ARR.
Recording Bookings
When a contract is signed, or an order is placed, it depends on how it’s handled. If the business receives cash prior to completing their monthly or yearly service expectation and say the contract is for $20,000 per month for 12 months, it would be recorded as follows:
Debit: Cash $240,000
Credit: Deferred Revenue $240,000
Since the contract has just been signed, but there’s been no product/service rendered, deferred or unearned, revenue has been created.
For every month that passes, the journal entry will progress as follows:
Debit: Deferred Revenue $20,000
Credit: Revenue $20,000
The deferred revenue account drops from $240,000 to $220,000, assuming the starting deferred revenue balance is even and there’s no deferred revenue.
The following month, the journal entries would be as follows:
Debit: Deferred Revenue $20,000
Credit: Revenue $20,000
This would occur every month until the end of the 12-month period.
Conclusion
When it comes to accounting for revenue, whether it’s booked, fulfilled by the company, or the payment received by the company, along with analyzing the time frame, it’s equally important to be familiar with the type of revenue it is for one to see how the company is performing.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
With a Roth IRA, the owner can make limited contributions each year. In 2025, the limit is $7,000; $8,000 if age 50 or older. Only people who earn less than $150,000 (single filers) or under $236,000 (married filing jointly) can make a full Roth IRA contribution. While contributions do not qualify for a tax deduction, earnings are not taxable once the account has been open for five years. Contributions, which were previously taxed as income, can be withdrawn at any time.
Once you open and contribute to a Roth IRA, the five-year countdown begins before you can take any earnings out tax-free. However, the holding period is actually measured from Jan. 1 of the year you made the first contribution.
For example, if you opened your Roth IRA on Dec. 31, 2024, the holding period backs up to Jan. 1, 2024. Therefore, your holding period is technically only four years instead of five to avoid paying taxes on earnings.
However, it gets even better because you are allowed to make a Roth contribution for the prior tax year up until tax day in April. That means if you open a Roth in April 2025 and designate your contribution for 2024, your holding period is shortened by another four months.
This is why it’s important to open a Roth as soon as possible, even if you cannot contribute a lot of money in the near future. It makes a great strategy for a high school or college student with job earnings to at least open a Roth for future use. While there is no upfront tax deduction, you may withdraw contributions penalty and tax-free at any time – which makes it ideal as both a liquid emergency account as well as long-term savings.
As for withdrawing earnings, the rules are trickier. As far as the IRS is concerned, contributions are withdrawn first and then earnings. Note that when earnings are withdrawn before age 59½, the amount is subject to both taxes and a 10 percent penalty, but there are exceptions that waive the penalty. For example, if your account is less than five years old, you can still withdraw earnings (penalty-free but still subject to taxes) for the following purposes:
To help pay for a first-time home purchase (up to $10,000)
To pay for college
To pay certain emergency expenses
To pay for expenses in connection with a federally qualified disaster
To pay expenses related to a birth or adoption
To pay for unreimbursed medical expenses or health insurance if unemployed
If you become disabled or are a survivor of domestic abuse
If your account is older than five years, you can avoid both taxes and the penalty if the funds are used to help pay for a first-time home purchase (up to $10,000) or if you become disabled.
After age 59½, there are no taxes and no penalties for any money withdrawn from a Roth IRA for any reason.
Multiple Roths
The same five-year holding period applies to all the Roths you own, with the clock starting at the first contribution to your first Roth. This means that if five years after the date you open your first Roth, you open a new Roth and contribute a bunch of income, you won’t have to wait another five years to tap those earnings tax-free. This perk does not apply to a Roth 401(k) account, which maintains a separate five-year holding period.
Conversion Benefits
When you convert a traditional IRA or 401(k) to a Roth (assuming your plan allows in-service withdrawals or in-plan conversions), you must pay income taxes in the year the money is converted. However, there are some very good reasons to convert:
Tax-Free Income – By converting assets when you’re still working, you can pay the taxes owed with current income, but from that point on, the Roth IRA will grow tax-free. This is particularly helpful in diversifying your tax liability during retirement if you have other income sources (e.g., pension, brokerage account, Social Security).
Eliminate RMDs – If you continue working into your 70s, you may continue contributing to your Roth IRA, and assets converted from a 401(k) or traditional IRA are no longer subject to required minimum distributions. This way, your full account balance has the opportunity to continue growing for later retirement and/or for your heirs.
Be aware that converting a taxable retirement account to a Roth IRA begins its own five-year timetable, so convert long before you need to begin withdrawals.
Alan F Burke CPA
Rules of the Roth
February 1, 2025 · Blog, Financial Planning
⏱ 4 min read
With a Roth IRA, the owner can make limited contributions each year. In 2025, the limit is $7,000; $8,000 if age 50 or older. Only people who earn less than $150,000 (single filers) or under $236,000 (married filing jointly) can make a full Roth IRA contribution. While contributions do not qualify for a tax deduction, earnings are not taxable once the account has been open for five years. Contributions, which were previously taxed as income, can be withdrawn at any time.
Once you open and contribute to a Roth IRA, the five-year countdown begins before you can take any earnings out tax-free. However, the holding period is actually measured from Jan. 1 of the year you made the first contribution.
For example, if you opened your Roth IRA on Dec. 31, 2024, the holding period backs up to Jan. 1, 2024. Therefore, your holding period is technically only four years instead of five to avoid paying taxes on earnings.
However, it gets even better because you are allowed to make a Roth contribution for the prior tax year up until tax day in April. That means if you open a Roth in April 2025 and designate your contribution for 2024, your holding period is shortened by another four months.
This is why it’s important to open a Roth as soon as possible, even if you cannot contribute a lot of money in the near future. It makes a great strategy for a high school or college student with job earnings to at least open a Roth for future use. While there is no upfront tax deduction, you may withdraw contributions penalty and tax-free at any time – which makes it ideal as both a liquid emergency account as well as long-term savings.
As for withdrawing earnings, the rules are trickier. As far as the IRS is concerned, contributions are withdrawn first and then earnings. Note that when earnings are withdrawn before age 59½, the amount is subject to both taxes and a 10 percent penalty, but there are exceptions that waive the penalty. For example, if your account is less than five years old, you can still withdraw earnings (penalty-free but still subject to taxes) for the following purposes:
To help pay for a first-time home purchase (up to $10,000)
To pay for college
To pay certain emergency expenses
To pay for expenses in connection with a federally qualified disaster
To pay expenses related to a birth or adoption
To pay for unreimbursed medical expenses or health insurance if unemployed
If you become disabled or are a survivor of domestic abuse
If your account is older than five years, you can avoid both taxes and the penalty if the funds are used to help pay for a first-time home purchase (up to $10,000) or if you become disabled.
After age 59½, there are no taxes and no penalties for any money withdrawn from a Roth IRA for any reason.
Multiple Roths
The same five-year holding period applies to all the Roths you own, with the clock starting at the first contribution to your first Roth. This means that if five years after the date you open your first Roth, you open a new Roth and contribute a bunch of income, you won’t have to wait another five years to tap those earnings tax-free. This perk does not apply to a Roth 401(k) account, which maintains a separate five-year holding period.
Conversion Benefits
When you convert a traditional IRA or 401(k) to a Roth (assuming your plan allows in-service withdrawals or in-plan conversions), you must pay income taxes in the year the money is converted. However, there are some very good reasons to convert:
Tax-Free Income – By converting assets when you’re still working, you can pay the taxes owed with current income, but from that point on, the Roth IRA will grow tax-free. This is particularly helpful in diversifying your tax liability during retirement if you have other income sources (e.g., pension, brokerage account, Social Security).
Eliminate RMDs – If you continue working into your 70s, you may continue contributing to your Roth IRA, and assets converted from a 401(k) or traditional IRA are no longer subject to required minimum distributions. This way, your full account balance has the opportunity to continue growing for later retirement and/or for your heirs.
Be aware that converting a taxable retirement account to a Roth IRA begins its own five-year timetable, so convert long before you need to begin withdrawals.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.
Innocent spouse relief allows you to avoid being held responsible for tax debts, penalties, and interest stemming from a joint tax filing. In the case that a spouse (or ex-spouse) made an error that led to a tax issue, regardless of intention, you may not have to shoulder the burden. Say your income wasn’t reported, excessive deductions were claimed, or tax fraud was committed. If you meet the IRS criteria, you can request relief by submitting Form 8857.
Qualifications for Innocent Spouse Relief
To qualify, you must meet several conditions.
Joint Tax Return: The tax liability must arise from a joint return. When you file together, both spouses are equally responsible for any tax issues that arise.
Tax Underreporting: The tax issue must stem from underreported income or an incorrect claim for deductions or credits. This could involve unreported income (like from offshore accounts) or fraudulent deductions made by your spouse.
Lack of Knowledge: You must show that, at the time of filing, you were unaware of the problem and had no reason to suspect it.
Unfair Responsibility: Lastly, it must be deemed unjust to hold you liable. The IRS looks at factors such as whether you benefited from the underreported taxes (e.g., through extravagant spending) or if you’ve divorced.
What Doesn’t Qualify for Innocent Spouse Relief?
Not all cases involving a spouse’s financial mismanagement qualify for relief. The IRS may reject your claim in the following situations:
Awareness of the Mistake: If you knew about the issue or should have known, you won’t be eligible for relief. Simply stating that you didn’t read the return won’t suffice. The IRS expects you to recognize obvious errors if you have access to the relevant information.
Divorce Doesn’t Automatically Provide Relief: Divorce alone doesn’t eliminate your liability for tax debt. Joint returns create shared responsibility, and being separated or divorced doesn’t mean the IRS will automatically release you from this obligation. You must prove your innocence through the relief process.
Disagreements Over Personal Spending: If your spouse’s spending decisions are something you disagree with, the IRS will not consider it a tax issue unless it involves unreported income or fraudulent deductions. The IRS focuses on tax matters, not marital conflicts over financial choices.
Pros and Cons of Filing
Advantages include:
Avoid Financial Hardship: Tax liabilities, along with interest and penalties, can be overwhelming. Innocent spouse relief can protect you from these financial burdens.
Clear Your Name: If you’ve been unfairly tied to a tax issue you didn’t cause, the relief process can help remove you from the responsibility.
Peace of Mind: Successfully claiming relief can bring emotional relief, especially if you’ve gone through a challenging marriage.
Potential drawbacks are:
No Guarantee of Approval: The IRS does not grant relief easily. You’ll need to provide strong evidence, and the process can be lengthy and difficult.
Time Limitations: You generally must apply for relief within two years of the IRS starting collection efforts. Missing this deadline could result in losing the opportunity for relief.
Invasive Process: The IRS will closely examine your financial and personal life, including details about your marriage and finances, which could feel intrusive if you value your privacy.
Possible Strain on Relationships: If you’re still married, filing for relief could cause tension, as it might be seen as blaming your spouse for the tax issue.
Conclusion
To request innocent spouse relief, you’ll need to file Form 8857. Be prepared to provide details about the tax years involved, explain why you didn’t know about the issue, and any supporting documents (like bank statements, emails, or divorce decrees.
After submitting the form, the IRS will notify your spouse or ex-spouse, who will have a chance to respond by a specific date.
Alan F Burke CPA
What is Innocent Spouse Relief?
January 1, 2025 · Blog, Tax and Financial News
⏱ 4 min read
The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.
Innocent spouse relief allows you to avoid being held responsible for tax debts, penalties, and interest stemming from a joint tax filing. In the case that a spouse (or ex-spouse) made an error that led to a tax issue, regardless of intention, you may not have to shoulder the burden. Say your income wasn’t reported, excessive deductions were claimed, or tax fraud was committed. If you meet the IRS criteria, you can request relief by submitting Form 8857.
Qualifications for Innocent Spouse Relief
To qualify, you must meet several conditions.
Joint Tax Return: The tax liability must arise from a joint return. When you file together, both spouses are equally responsible for any tax issues that arise.
Tax Underreporting: The tax issue must stem from underreported income or an incorrect claim for deductions or credits. This could involve unreported income (like from offshore accounts) or fraudulent deductions made by your spouse.
Lack of Knowledge: You must show that, at the time of filing, you were unaware of the problem and had no reason to suspect it.
Unfair Responsibility: Lastly, it must be deemed unjust to hold you liable. The IRS looks at factors such as whether you benefited from the underreported taxes (e.g., through extravagant spending) or if you’ve divorced.
What Doesn’t Qualify for Innocent Spouse Relief?
Not all cases involving a spouse’s financial mismanagement qualify for relief. The IRS may reject your claim in the following situations:
Awareness of the Mistake: If you knew about the issue or should have known, you won’t be eligible for relief. Simply stating that you didn’t read the return won’t suffice. The IRS expects you to recognize obvious errors if you have access to the relevant information.
Divorce Doesn’t Automatically Provide Relief: Divorce alone doesn’t eliminate your liability for tax debt. Joint returns create shared responsibility, and being separated or divorced doesn’t mean the IRS will automatically release you from this obligation. You must prove your innocence through the relief process.
Disagreements Over Personal Spending: If your spouse’s spending decisions are something you disagree with, the IRS will not consider it a tax issue unless it involves unreported income or fraudulent deductions. The IRS focuses on tax matters, not marital conflicts over financial choices.
Pros and Cons of Filing
Advantages include:
Avoid Financial Hardship: Tax liabilities, along with interest and penalties, can be overwhelming. Innocent spouse relief can protect you from these financial burdens.
Clear Your Name: If you’ve been unfairly tied to a tax issue you didn’t cause, the relief process can help remove you from the responsibility.
Peace of Mind: Successfully claiming relief can bring emotional relief, especially if you’ve gone through a challenging marriage.
Potential drawbacks are:
No Guarantee of Approval: The IRS does not grant relief easily. You’ll need to provide strong evidence, and the process can be lengthy and difficult.
Time Limitations: You generally must apply for relief within two years of the IRS starting collection efforts. Missing this deadline could result in losing the opportunity for relief.
Invasive Process: The IRS will closely examine your financial and personal life, including details about your marriage and finances, which could feel intrusive if you value your privacy.
Possible Strain on Relationships: If you’re still married, filing for relief could cause tension, as it might be seen as blaming your spouse for the tax issue.
Conclusion
To request innocent spouse relief, you’ll need to file Form 8857. Be prepared to provide details about the tax years involved, explain why you didn’t know about the issue, and any supporting documents (like bank statements, emails, or divorce decrees.
After submitting the form, the IRS will notify your spouse or ex-spouse, who will have a chance to respond by a specific date.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.

 With the number of Amazon Prime member subscribers growing from 58 million in 2016 to 180 million in 2024, according to Statista, there’s a sustained recurring subscription model that one of America’s most successful retailers has increased more than 200 percent in eight years. Whether it’s a large company such as Amazon or a solopreneur beginning their recurring subscription services, it’s important to first distinguish between overall bookings and recurring revenue; and then to illustrate how businesses can measure these two types of revenue.



 With a Roth IRA, the owner can make limited contributions each year. In 2025, the limit is $7,000; $8,000 if age 50 or older. Only people who earn less than $150,000 (single filers) or under $236,000 (married filing jointly) can make a full Roth IRA contribution. While contributions do not qualify for a tax deduction, earnings are not taxable once the account has been open for five years. Contributions, which were previously taxed as income, can be withdrawn at any time.
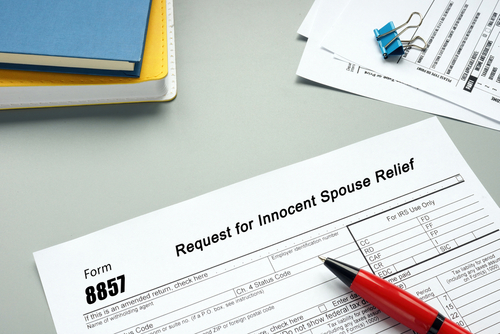 The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.