Annuities are one of many products that folks have in their nest egg. But first, what exactly is an annuity?
Simply put, it’s a contract with an insurance company that promises to pay the buyer a steady stream of income in the future. It can be either a fixed or variable income stream. The term “annuity” can also refer to a sum of money payable yearly or at other regular intervals.
There are some things to know before you charge headlong into putting your assets into an annuity. So, here are a few watchouts to consider before you head in that direction.
Ask the Right Questions
First up, what kind of annuity is it? What about the fees and optional riders? Is there a Market Value Adjustment, aka MVA? What is the AM Best rating and Comdex rating? How long is the rate guaranteed? How much can you take out penalty-free? How is the gain calculated for index annuities? Is there a surrender charge assessed if I die? How long is the contract term? How is their service? Lots of questions, yes, but the more you ask, the better.
Learn About New Features and Products
Here’s something interesting to ponder: Did you know that 99 percent of index annuities don’t include dividends? Or that 99 percent of index annuities only lock in the rates for 1 to 2 years? In fact, there are new products that include dividends and lock-in rates for the length of the term. Who knew? Here’s a list of the 10 best annuity companies as of September 2024 you might want to check out.
Vet the History of the Company
This is key. For instance, how long have they held their AM Best rating? How long have they been operating under their current name? And finally, did you know that start-ups buy shell companies formed 75+ years ago to advertise they’ve been around since then? Yep, make sure you do your research.
Watch Out for Fees on Variable Annuities
Here’s the thing: Variable annuities have lots of different layers of fees. Make sure you secure an itemized breakdown of all of the fees before you commit. If your variable annuity earns 7 percent to 9 percent gross and you pay 3 percent to 4 percent in fees, you might be better off in a fixed-rate product.
Check Out Long-Term Care Riders
Believe it or not, some annuities offer 200 percent to 300 percent of your initial deposit in long-term care benefits with an optional rider. In fact, long-term care riders on life insurance policies can be more affordable than standalone long-term care policies. However, should you not utilizeyour long-term care benefits, your heirs will get the full death benefit from your life insurance policy, less what you owe on any of your policy loans.
Take a Look at All Types of Annuities
Typically, most banks sell only five to eight annuity companies. So don’t rely on just your bank. If you do, you’ll miss out on 95 percent of the products that are out there. And this is important to know: Lots of insurance agents and “advisors” focus on selling a few index or variable annuities. Make sure you shop around before buying.
Annuities are just one of many diversified assets you might want to include in your investment portfolio – as you know, diversity is crucial. But when it comes to annuities, there are specific questions and things to think about. Make sure you do your due diligence before you invest.
Sources
11 Annuity Tips You Should Know (annuityresources.org)
Long-Term Care Rider: What It Is, How It Works (investopedia.com)
Alan F Burke CPA
6 Things To Know About Annuities
October 1, 2024 · Blog, Tip of the Month
⏱ 4 min read
Annuities are one of many products that folks have in their nest egg. But first, what exactly is an annuity?
Simply put, it’s a contract with an insurance company that promises to pay the buyer a steady stream of income in the future. It can be either a fixed or variable income stream. The term “annuity” can also refer to a sum of money payable yearly or at other regular intervals.
There are some things to know before you charge headlong into putting your assets into an annuity. So, here are a few watchouts to consider before you head in that direction.
Ask the Right Questions
First up, what kind of annuity is it? What about the fees and optional riders? Is there a Market Value Adjustment, aka MVA? What is the AM Best rating and Comdex rating? How long is the rate guaranteed? How much can you take out penalty-free? How is the gain calculated for index annuities? Is there a surrender charge assessed if I die? How long is the contract term? How is their service? Lots of questions, yes, but the more you ask, the better.
Learn About New Features and Products
Here’s something interesting to ponder: Did you know that 99 percent of index annuities don’t include dividends? Or that 99 percent of index annuities only lock in the rates for 1 to 2 years? In fact, there are new products that include dividends and lock-in rates for the length of the term. Who knew? Here’s a list of the 10 best annuity companies as of September 2024 you might want to check out.
Vet the History of the Company
This is key. For instance, how long have they held their AM Best rating? How long have they been operating under their current name? And finally, did you know that start-ups buy shell companies formed 75+ years ago to advertise they’ve been around since then? Yep, make sure you do your research.
Watch Out for Fees on Variable Annuities
Here’s the thing: Variable annuities have lots of different layers of fees. Make sure you secure an itemized breakdown of all of the fees before you commit. If your variable annuity earns 7 percent to 9 percent gross and you pay 3 percent to 4 percent in fees, you might be better off in a fixed-rate product.
Check Out Long-Term Care Riders
Believe it or not, some annuities offer 200 percent to 300 percent of your initial deposit in long-term care benefits with an optional rider. In fact, long-term care riders on life insurance policies can be more affordable than standalone long-term care policies. However, should you not utilizeyour long-term care benefits, your heirs will get the full death benefit from your life insurance policy, less what you owe on any of your policy loans.
Take a Look at All Types of Annuities
Typically, most banks sell only five to eight annuity companies. So don’t rely on just your bank. If you do, you’ll miss out on 95 percent of the products that are out there. And this is important to know: Lots of insurance agents and “advisors” focus on selling a few index or variable annuities. Make sure you shop around before buying.
Annuities are just one of many diversified assets you might want to include in your investment portfolio – as you know, diversity is crucial. But when it comes to annuities, there are specific questions and things to think about. Make sure you do your due diligence before you invest.
Sources
11 Annuity Tips You Should Know (annuityresources.org)
Long-Term Care Rider: What It Is, How It Works (investopedia.com)
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
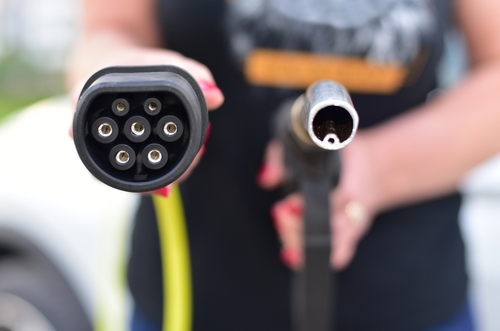
With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.
This statistic is important because it illustrates how assets can be rendered less useful and potentially turn into stranded assets. A stranded asset, defined, is an asset that’s no longer able to provide its owner the profitable payback they originally expected. The difference is based on shifts, primarily negative, that impact the asset’s expected productive performance.
How & Why Assets Become Stranded
When an asset loses its earning power, normally due to extraneous circumstances, like the invention of a more efficient battery, it can become stranded. For example, a machine that’s exclusively capable of making an internal combustion engine (ICE) vehicle can be considered stranded as the transition to electric vehicles (EV) is made. Since the machine is less valuable because it makes fewer and fewer ICE vehicles, it could be impaired or stranded.
This example illustrates that new technology, especially one that moves forward, can render equipment less useful than previously expected. Other ways assets can be stranded include administrative modifications, evolving societal conventions, etc.
Considerations for Stranded Assets by Testing an Asset for Impairment
The primary way to establish if an asset is stranded is to run an impairment test on it. Stranded assets impact the income statement via a non-cash loss, along with impacting the balance sheet by reducing asset value. Therefore, companies must report a loss on the income statement as it’s completely written off the balance sheet.
Whether it’s through the lens of International Financial Reporting Standards (IFRS) or generally accepted accounting principles (GAAP), whether an asset is intangible or tangible, when its value issue is less than book value or impaired, it must be written down.
GAAP Standard
The first step is to determine the carrying value. This is calculated by subtracting the accumulated depreciation from the asset’s original cost. From there, the asset’s projected undiscounted future cash flows (UFCF) are analyzed against the asset’s carrying value. If the total UFCF is less than the carrying value, an asset is considered impaired.
IFRS Standard
The first step also looks at an asset’s carrying value. From there, if either of the following two values is lower than the carrying value, it’s considered impaired:
Present value of future cash flows generated by the asset (the so-called “fair value in use” consideration)
Fair value less costs to sell the asset
Financial Statement Considerations
If an asset is impaired or stranded, whatever amount the asset drops by, it lowers the business’ asset’s value on the balance sheet. Looking at the income statement, it’s considered a loss. Additionally, since a devaluation is not considered a cash event, it doesn’t trigger any cash outflows. A real-world example can better illustrate this.
The following assumes a business reports its accounting under GAAP. It could be a company that produces fracking equipment to recover natural gas and crude oil. With the uncertainty of domestic fossil fuel policy, specifically where land can be explored, the threat of OPEC and/or Iran being able to determine their production, and the threat of increased government spending on green energy, fracking equipment has a current carrying value of $10 million. However, with increased competition from the three different factors, the same assets can produce an aggregate of $7.5 million in undiscounted future cash flows.
Based on GAAP, since the carrying value is $2.5 million more than the total undiscounted future cash flows, the business would need to record the same amount for an impairment loss. The journal entries would be:
Loss from Impairment Debit:. $2.5 million
Provision for Impairment Losses Credit: $2.5 million
Conclusion
When it comes to accounting for stranded assets, it’s important to ensure guidelines are followed based on the type of accounting standards businesses must follow.
Alan F Burke CPA
How to Account for Stranded Assets
October 1, 2024 · Accounting News, Blog
⏱ 4 min read
With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.
This statistic is important because it illustrates how assets can be rendered less useful and potentially turn into stranded assets. A stranded asset, defined, is an asset that’s no longer able to provide its owner the profitable payback they originally expected. The difference is based on shifts, primarily negative, that impact the asset’s expected productive performance.
How & Why Assets Become Stranded
When an asset loses its earning power, normally due to extraneous circumstances, like the invention of a more efficient battery, it can become stranded. For example, a machine that’s exclusively capable of making an internal combustion engine (ICE) vehicle can be considered stranded as the transition to electric vehicles (EV) is made. Since the machine is less valuable because it makes fewer and fewer ICE vehicles, it could be impaired or stranded.
This example illustrates that new technology, especially one that moves forward, can render equipment less useful than previously expected. Other ways assets can be stranded include administrative modifications, evolving societal conventions, etc.
Considerations for Stranded Assets by Testing an Asset for Impairment
The primary way to establish if an asset is stranded is to run an impairment test on it. Stranded assets impact the income statement via a non-cash loss, along with impacting the balance sheet by reducing asset value. Therefore, companies must report a loss on the income statement as it’s completely written off the balance sheet.
Whether it’s through the lens of International Financial Reporting Standards (IFRS) or generally accepted accounting principles (GAAP), whether an asset is intangible or tangible, when its value issue is less than book value or impaired, it must be written down.
GAAP Standard
The first step is to determine the carrying value. This is calculated by subtracting the accumulated depreciation from the asset’s original cost. From there, the asset’s projected undiscounted future cash flows (UFCF) are analyzed against the asset’s carrying value. If the total UFCF is less than the carrying value, an asset is considered impaired.
IFRS Standard
The first step also looks at an asset’s carrying value. From there, if either of the following two values is lower than the carrying value, it’s considered impaired:
Present value of future cash flows generated by the asset (the so-called “fair value in use” consideration)
Fair value less costs to sell the asset
Financial Statement Considerations
If an asset is impaired or stranded, whatever amount the asset drops by, it lowers the business’ asset’s value on the balance sheet. Looking at the income statement, it’s considered a loss. Additionally, since a devaluation is not considered a cash event, it doesn’t trigger any cash outflows. A real-world example can better illustrate this.
The following assumes a business reports its accounting under GAAP. It could be a company that produces fracking equipment to recover natural gas and crude oil. With the uncertainty of domestic fossil fuel policy, specifically where land can be explored, the threat of OPEC and/or Iran being able to determine their production, and the threat of increased government spending on green energy, fracking equipment has a current carrying value of $10 million. However, with increased competition from the three different factors, the same assets can produce an aggregate of $7.5 million in undiscounted future cash flows.
Based on GAAP, since the carrying value is $2.5 million more than the total undiscounted future cash flows, the business would need to record the same amount for an impairment loss. The journal entries would be:
Loss from Impairment Debit:. $2.5 million
Provision for Impairment Losses Credit: $2.5 million
Conclusion
When it comes to accounting for stranded assets, it’s important to ensure guidelines are followed based on the type of accounting standards businesses must follow.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Social media has become a powerful tool for helping businesses reach their prospects and customers. By using social media, a business can connect with its audience, build brand awareness, and drive sales. However, many struggle to convert social media engagement – likes, shares, comments, and followers – into tangible business opportunities. Transforming these engagements into actionable leads and sales is where the real power of social media lies. To successfully unlock this potential, businesses must effectively use social media analytics.
Understanding Social Media Analytics
Social media analytics involves gathering and analyzing data from social media platforms to help make informed business decisions. This data includes metrics such as engagement rates, reach, impressions, follower growth, and sentiment analysis, among others. By understanding what this data signifies, businesses can gain valuable insights into the behavior, preferences, and needs of their audience. These insights are then used to tailor marketing strategies, create more relevant content, and improve customer interactions.
The Shift from Vanity Metrics to Meaningful Insights
Sometimes, it’s easy to get caught up in vanity metrics, such as the number of likes or followers. It is important to note that these metrics do not necessarily translate to sales. To convert social media engagement into leads, businesses need to focus on meaningful insights that reveal how engaged their audience is and how this engagement can be leveraged.
For instance, instead of focusing on the number of likes, businesses should analyze which types of posts are receiving the most engagement and why. This includes checking the topics, formats or times of day that generate more interest and engagement. By identifying patterns and trends, businesses can enhance their content strategy to focus on what resonates most with their audience.
Identifying and Nurturing Potential Leads
After having a better understanding of what drives engagement, businesses can begin to identify potential leads within their social media audience. This is where advanced analytics tools come into play. Tools that track and analyze individual user interactions will help identify users who consistently engage with posted content.
For example, a user who frequently comments on posts, shares content, or clicks on links may demonstrate a strong interest in the business’s products or services. Businesses can categorize such users as potential leads. More focus is placed on this category by nurturing them through personalized content, direct engagement, and targeted offers.
It is also good to note that social media analytics is a powerful tool for analyzing competitors’ strategies, too. By monitoring their comment sections, a business can identify gaps or unmet needs in their audience that present opportunities to capture market share.
Leveraging Social Media Ads for Lead Generation
Social media advertising is another effective way to convert social media engagement into leads. Platforms like Facebook, Instagram, LinkedIn, and X (formerly Twitter) offer advanced targeting options that allow businesses to create highly personalized ad campaigns based on user data. Businesses can create ads specifically designed to appeal to their most engaged followers.
For instance, if analytics reveal that a particular segment of followers is highly interested in a specific product, businesses can create ads that feature this product and offer a special promotion or discount.
Turning Engagement into Sales Through Conversion Optimization
Once potential leads are identified and targeted through ads or personalized content, the next step is to optimize the conversion process. This involves ensuring a seamless journey from social media engagement to lead capture and eventual sale. A critical aspect of this process is the landing page – a dedicated page on the business’s website designed to capture leads.
The landing pages must be tailored to match the expectations set by the social media content or ads that drove the traffic. For example, if an ad on a social media platform promises a free or discounted offer, the landing page should prominently feature this offer. Additionally, it helps A/B test different landing page designs, headlines and calls to action to identify the most effective strategies.
Using Analytics to Measure and Improve ROI
Unlike traditional marketing channels, social media analytics can track and measure the effectiveness of marketing campaigns. By tracking key performance indicators (KPIs) such as reach, click-through rates, conversions, and cost per lead, businesses can measure the effectiveness of their social media campaigns and make necessary adjustments.
Continuous monitoring and optimization ensure that social media efforts drive engagement and contribute to the business’s bottom line.
In conclusion, converting social media engagement into actionable leads and sales opportunities requires a strategic approach leveraging social media analytics’ power. Businesses can tailor their content, identify and nurture potential leads, and optimize their conversion strategies by moving beyond vanity metrics and focusing on meaningful insights. This will ultimately drive business growth and success in today’s competitive digital landscape.
Alan F Burke CPA
From Likes to Leads: Converting Social Media Analytics into Business Opportunities
September 1, 2024 · Blog, What's New in Technology
⏱ 4 min read
Social media has become a powerful tool for helping businesses reach their prospects and customers. By using social media, a business can connect with its audience, build brand awareness, and drive sales. However, many struggle to convert social media engagement – likes, shares, comments, and followers – into tangible business opportunities. Transforming these engagements into actionable leads and sales is where the real power of social media lies. To successfully unlock this potential, businesses must effectively use social media analytics.
Understanding Social Media Analytics
Social media analytics involves gathering and analyzing data from social media platforms to help make informed business decisions. This data includes metrics such as engagement rates, reach, impressions, follower growth, and sentiment analysis, among others. By understanding what this data signifies, businesses can gain valuable insights into the behavior, preferences, and needs of their audience. These insights are then used to tailor marketing strategies, create more relevant content, and improve customer interactions.
The Shift from Vanity Metrics to Meaningful Insights
Sometimes, it’s easy to get caught up in vanity metrics, such as the number of likes or followers. It is important to note that these metrics do not necessarily translate to sales. To convert social media engagement into leads, businesses need to focus on meaningful insights that reveal how engaged their audience is and how this engagement can be leveraged.
For instance, instead of focusing on the number of likes, businesses should analyze which types of posts are receiving the most engagement and why. This includes checking the topics, formats or times of day that generate more interest and engagement. By identifying patterns and trends, businesses can enhance their content strategy to focus on what resonates most with their audience.
Identifying and Nurturing Potential Leads
After having a better understanding of what drives engagement, businesses can begin to identify potential leads within their social media audience. This is where advanced analytics tools come into play. Tools that track and analyze individual user interactions will help identify users who consistently engage with posted content.
For example, a user who frequently comments on posts, shares content, or clicks on links may demonstrate a strong interest in the business’s products or services. Businesses can categorize such users as potential leads. More focus is placed on this category by nurturing them through personalized content, direct engagement, and targeted offers.
It is also good to note that social media analytics is a powerful tool for analyzing competitors’ strategies, too. By monitoring their comment sections, a business can identify gaps or unmet needs in their audience that present opportunities to capture market share.
Leveraging Social Media Ads for Lead Generation
Social media advertising is another effective way to convert social media engagement into leads. Platforms like Facebook, Instagram, LinkedIn, and X (formerly Twitter) offer advanced targeting options that allow businesses to create highly personalized ad campaigns based on user data. Businesses can create ads specifically designed to appeal to their most engaged followers.
For instance, if analytics reveal that a particular segment of followers is highly interested in a specific product, businesses can create ads that feature this product and offer a special promotion or discount.
Turning Engagement into Sales Through Conversion Optimization
Once potential leads are identified and targeted through ads or personalized content, the next step is to optimize the conversion process. This involves ensuring a seamless journey from social media engagement to lead capture and eventual sale. A critical aspect of this process is the landing page – a dedicated page on the business’s website designed to capture leads.
The landing pages must be tailored to match the expectations set by the social media content or ads that drove the traffic. For example, if an ad on a social media platform promises a free or discounted offer, the landing page should prominently feature this offer. Additionally, it helps A/B test different landing page designs, headlines and calls to action to identify the most effective strategies.
Using Analytics to Measure and Improve ROI
Unlike traditional marketing channels, social media analytics can track and measure the effectiveness of marketing campaigns. By tracking key performance indicators (KPIs) such as reach, click-through rates, conversions, and cost per lead, businesses can measure the effectiveness of their social media campaigns and make necessary adjustments.
Continuous monitoring and optimization ensure that social media efforts drive engagement and contribute to the business’s bottom line.
In conclusion, converting social media engagement into actionable leads and sales opportunities requires a strategic approach leveraging social media analytics’ power. Businesses can tailor their content, identify and nurture potential leads, and optimize their conversion strategies by moving beyond vanity metrics and focusing on meaningful insights. This will ultimately drive business growth and success in today’s competitive digital landscape.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.

 Annuities are one of many products that folks have in their nest egg. But first, what exactly is an annuity?



 With more than 14 million electric vehicle (EV) registrations in 2023 worldwide and 2023 seeing an increase in EV sales over 2022 by 35 percent, manufacturers are probably happy – but not those producing the traditional internal combustion engine (ICE) vehicles. This is according to the International Energy Agency’s Global EV Outlook 2024: Trends in Electric Cars.
 Social media has become a powerful tool for helping businesses reach their prospects and customers. By using social media, a business can connect with its audience, build brand awareness, and drive sales. However, many struggle to convert social media engagement – likes, shares, comments, and followers – into tangible business opportunities. Transforming these engagements into actionable leads and sales is where the real power of social media lies. To successfully unlock this potential, businesses must effectively use social media analytics.