The Salt Typhoon cyberattack is among recent cyberattacks that reaffirm the urgent need for robust data security measures. This attack targeted major telecommunications providers, compromising critical infrastructure and potentially exposing vast amounts of sensitive data. With cyberthreats becoming more sophisticated, businesses and individuals must prioritize data security to maintain trust and compliance.
The Role of Apps in Managing and Protecting Client Data
Businesses need apps because they make the work easier and more organized. Apps help teams communicate better, manage tasks, and share information quickly, no matter where people are. The apps also simplify handling customer needs, improving service, and tracking business performance. Generally, apps save time while helping businesses work smarter and stay competitive.
One of the most critical uses of apps is managing client data. This data includes personal details like names and addresses. It also includes financial information such as bank details, as well as business-specific data like contracts and project plans. Losing or exposing this sensitive information can lead to severe consequences, including financial losses, legal penalties, and damaged reputations. Clients may lose trust in your business, leading to lost opportunities and reduced customer loyalty. By using apps effectively, businesses can better organize, safeguard, and utilize client data to build stronger relationships and maintain long-term success.
Encryption: A Critical Security Measure
Encryption has become crucial in modern data security. It transforms readable data into an unreadable format, ensuring only authorized parties can access the information. There are various types of encryptions, including end-to-end encryption (E2EE), which protects data during transmission, and at-rest encryption, which secures stored data.
Following the Salt Typhoon cyberattacks, the FBI and Cybersecurity and Infrastructure Security Agency (CISA) issued a joint advisory urging individuals and organizations to prioritize using encrypted communication channels. Given the vulnerability of traditional communication methods, the agencies strongly recommended adopting end-to-end encrypted messaging apps like Signal for secure communication. This recommendation aims to mitigate the risks associated with compromised telecommunication networks. It also helps protect sensitive information from unauthorized access. Even if cybercriminals intercept the data, they cannot decipher it without the encryption key. This layer of protection mitigates the risks of unauthorized access and data breaches, making encryption an essential tool for businesses.
The Role of Encrypted Apps
Enhanced security: Encrypted apps provide a critical layer of defense against sophisticated cyberattacks. By encrypting data both in transit and at rest, these apps ensure that even if communication networks are compromised, sensitive information remains inaccessible to attackers.
Compliance with regulations: With so many ongoing cyberattacks, regulatory scrutiny of data security practices has intensified. Encrypted apps can help businesses comply with relevant regulations, such as the GDPR and CCPA, by demonstrating a commitment to data protection.
Building trust and customer loyalty: Customers are increasingly wary of data breaches in an era of heightened cybersecurity concerns. Utilizing encrypted apps demonstrates a commitment to data security and privacy, fostering trust and loyalty among clients.
Protecting business operations: Encrypted apps are crucial for protecting client data and safeguarding critical business information, such as intellectual property, financial records, and internal communications. This ensures the continuity and integrity of business operations, even in the face of advanced cyber threats.
Choosing and Implementing Encrypted Apps
When selecting and implementing the right encrypted apps, it is important to consider them carefully. First, it is good to consider industry-specific needs as different industries have different data security needs. For example, while a healthcare provider must comply with Health Insurance Portability and Accountability Act (HIPAA) regulations, a business in the financial industry must adhere to banking regulations. This calls for selecting industry-specific apps.
Businesses also must prioritize apps with robust security features, such as strong encryption algorithms, multifactor authentication, and regular security updates. It is also important to carefully review the data privacy policies of app providers and ensure compliance with relevant regulations.
Effective employee training is also essential for successfully implementing encrypted apps. Employees must be educated on the importance of data security, the proper use of encrypted apps, and best practices for handling sensitive information.
Conclusion
Client data is one of a business’s most valuable assets, and protecting it is paramount. The growing threat of cyberattacks and the increasing complexity of data protection regulations make encryption an essential tool. By embracing encrypted communication channels, businesses can significantly enhance their resilience against sophisticated cyberattacks, protect sensitive client data, and maintain a competitive edge in today’s digital economy.
Alan F Burke CPA
Securing Client Data: The Importance of Encrypted Apps
January 1, 2025 · Blog, What's New in Technology
⏱ 4 min read
The Salt Typhoon cyberattack is among recent cyberattacks that reaffirm the urgent need for robust data security measures. This attack targeted major telecommunications providers, compromising critical infrastructure and potentially exposing vast amounts of sensitive data. With cyberthreats becoming more sophisticated, businesses and individuals must prioritize data security to maintain trust and compliance.
The Role of Apps in Managing and Protecting Client Data
Businesses need apps because they make the work easier and more organized. Apps help teams communicate better, manage tasks, and share information quickly, no matter where people are. The apps also simplify handling customer needs, improving service, and tracking business performance. Generally, apps save time while helping businesses work smarter and stay competitive.
One of the most critical uses of apps is managing client data. This data includes personal details like names and addresses. It also includes financial information such as bank details, as well as business-specific data like contracts and project plans. Losing or exposing this sensitive information can lead to severe consequences, including financial losses, legal penalties, and damaged reputations. Clients may lose trust in your business, leading to lost opportunities and reduced customer loyalty. By using apps effectively, businesses can better organize, safeguard, and utilize client data to build stronger relationships and maintain long-term success.
Encryption: A Critical Security Measure
Encryption has become crucial in modern data security. It transforms readable data into an unreadable format, ensuring only authorized parties can access the information. There are various types of encryptions, including end-to-end encryption (E2EE), which protects data during transmission, and at-rest encryption, which secures stored data.
Following the Salt Typhoon cyberattacks, the FBI and Cybersecurity and Infrastructure Security Agency (CISA) issued a joint advisory urging individuals and organizations to prioritize using encrypted communication channels. Given the vulnerability of traditional communication methods, the agencies strongly recommended adopting end-to-end encrypted messaging apps like Signal for secure communication. This recommendation aims to mitigate the risks associated with compromised telecommunication networks. It also helps protect sensitive information from unauthorized access. Even if cybercriminals intercept the data, they cannot decipher it without the encryption key. This layer of protection mitigates the risks of unauthorized access and data breaches, making encryption an essential tool for businesses.
The Role of Encrypted Apps
Enhanced security: Encrypted apps provide a critical layer of defense against sophisticated cyberattacks. By encrypting data both in transit and at rest, these apps ensure that even if communication networks are compromised, sensitive information remains inaccessible to attackers.
Compliance with regulations: With so many ongoing cyberattacks, regulatory scrutiny of data security practices has intensified. Encrypted apps can help businesses comply with relevant regulations, such as the GDPR and CCPA, by demonstrating a commitment to data protection.
Building trust and customer loyalty: Customers are increasingly wary of data breaches in an era of heightened cybersecurity concerns. Utilizing encrypted apps demonstrates a commitment to data security and privacy, fostering trust and loyalty among clients.
Protecting business operations: Encrypted apps are crucial for protecting client data and safeguarding critical business information, such as intellectual property, financial records, and internal communications. This ensures the continuity and integrity of business operations, even in the face of advanced cyber threats.
Choosing and Implementing Encrypted Apps
When selecting and implementing the right encrypted apps, it is important to consider them carefully. First, it is good to consider industry-specific needs as different industries have different data security needs. For example, while a healthcare provider must comply with Health Insurance Portability and Accountability Act (HIPAA) regulations, a business in the financial industry must adhere to banking regulations. This calls for selecting industry-specific apps.
Businesses also must prioritize apps with robust security features, such as strong encryption algorithms, multifactor authentication, and regular security updates. It is also important to carefully review the data privacy policies of app providers and ensure compliance with relevant regulations.
Effective employee training is also essential for successfully implementing encrypted apps. Employees must be educated on the importance of data security, the proper use of encrypted apps, and best practices for handling sensitive information.
Conclusion
Client data is one of a business’s most valuable assets, and protecting it is paramount. The growing threat of cyberattacks and the increasing complexity of data protection regulations make encryption an essential tool. By embracing encrypted communication channels, businesses can significantly enhance their resilience against sophisticated cyberattacks, protect sensitive client data, and maintain a competitive edge in today’s digital economy.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.
Innocent spouse relief allows you to avoid being held responsible for tax debts, penalties, and interest stemming from a joint tax filing. In the case that a spouse (or ex-spouse) made an error that led to a tax issue, regardless of intention, you may not have to shoulder the burden. Say your income wasn’t reported, excessive deductions were claimed, or tax fraud was committed. If you meet the IRS criteria, you can request relief by submitting Form 8857.
Qualifications for Innocent Spouse Relief
To qualify, you must meet several conditions.
Joint Tax Return: The tax liability must arise from a joint return. When you file together, both spouses are equally responsible for any tax issues that arise.
Tax Underreporting: The tax issue must stem from underreported income or an incorrect claim for deductions or credits. This could involve unreported income (like from offshore accounts) or fraudulent deductions made by your spouse.
Lack of Knowledge: You must show that, at the time of filing, you were unaware of the problem and had no reason to suspect it.
Unfair Responsibility: Lastly, it must be deemed unjust to hold you liable. The IRS looks at factors such as whether you benefited from the underreported taxes (e.g., through extravagant spending) or if you’ve divorced.
What Doesn’t Qualify for Innocent Spouse Relief?
Not all cases involving a spouse’s financial mismanagement qualify for relief. The IRS may reject your claim in the following situations:
Awareness of the Mistake: If you knew about the issue or should have known, you won’t be eligible for relief. Simply stating that you didn’t read the return won’t suffice. The IRS expects you to recognize obvious errors if you have access to the relevant information.
Divorce Doesn’t Automatically Provide Relief: Divorce alone doesn’t eliminate your liability for tax debt. Joint returns create shared responsibility, and being separated or divorced doesn’t mean the IRS will automatically release you from this obligation. You must prove your innocence through the relief process.
Disagreements Over Personal Spending: If your spouse’s spending decisions are something you disagree with, the IRS will not consider it a tax issue unless it involves unreported income or fraudulent deductions. The IRS focuses on tax matters, not marital conflicts over financial choices.
Pros and Cons of Filing
Advantages include:
Avoid Financial Hardship: Tax liabilities, along with interest and penalties, can be overwhelming. Innocent spouse relief can protect you from these financial burdens.
Clear Your Name: If you’ve been unfairly tied to a tax issue you didn’t cause, the relief process can help remove you from the responsibility.
Peace of Mind: Successfully claiming relief can bring emotional relief, especially if you’ve gone through a challenging marriage.
Potential drawbacks are:
No Guarantee of Approval: The IRS does not grant relief easily. You’ll need to provide strong evidence, and the process can be lengthy and difficult.
Time Limitations: You generally must apply for relief within two years of the IRS starting collection efforts. Missing this deadline could result in losing the opportunity for relief.
Invasive Process: The IRS will closely examine your financial and personal life, including details about your marriage and finances, which could feel intrusive if you value your privacy.
Possible Strain on Relationships: If you’re still married, filing for relief could cause tension, as it might be seen as blaming your spouse for the tax issue.
Conclusion
To request innocent spouse relief, you’ll need to file Form 8857. Be prepared to provide details about the tax years involved, explain why you didn’t know about the issue, and any supporting documents (like bank statements, emails, or divorce decrees.
After submitting the form, the IRS will notify your spouse or ex-spouse, who will have a chance to respond by a specific date.
Alan F Burke CPA
What is Innocent Spouse Relief?
January 1, 2025 · Blog, Tax and Financial News
⏱ 4 min read
The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.
Innocent spouse relief allows you to avoid being held responsible for tax debts, penalties, and interest stemming from a joint tax filing. In the case that a spouse (or ex-spouse) made an error that led to a tax issue, regardless of intention, you may not have to shoulder the burden. Say your income wasn’t reported, excessive deductions were claimed, or tax fraud was committed. If you meet the IRS criteria, you can request relief by submitting Form 8857.
Qualifications for Innocent Spouse Relief
To qualify, you must meet several conditions.
Joint Tax Return: The tax liability must arise from a joint return. When you file together, both spouses are equally responsible for any tax issues that arise.
Tax Underreporting: The tax issue must stem from underreported income or an incorrect claim for deductions or credits. This could involve unreported income (like from offshore accounts) or fraudulent deductions made by your spouse.
Lack of Knowledge: You must show that, at the time of filing, you were unaware of the problem and had no reason to suspect it.
Unfair Responsibility: Lastly, it must be deemed unjust to hold you liable. The IRS looks at factors such as whether you benefited from the underreported taxes (e.g., through extravagant spending) or if you’ve divorced.
What Doesn’t Qualify for Innocent Spouse Relief?
Not all cases involving a spouse’s financial mismanagement qualify for relief. The IRS may reject your claim in the following situations:
Awareness of the Mistake: If you knew about the issue or should have known, you won’t be eligible for relief. Simply stating that you didn’t read the return won’t suffice. The IRS expects you to recognize obvious errors if you have access to the relevant information.
Divorce Doesn’t Automatically Provide Relief: Divorce alone doesn’t eliminate your liability for tax debt. Joint returns create shared responsibility, and being separated or divorced doesn’t mean the IRS will automatically release you from this obligation. You must prove your innocence through the relief process.
Disagreements Over Personal Spending: If your spouse’s spending decisions are something you disagree with, the IRS will not consider it a tax issue unless it involves unreported income or fraudulent deductions. The IRS focuses on tax matters, not marital conflicts over financial choices.
Pros and Cons of Filing
Advantages include:
Avoid Financial Hardship: Tax liabilities, along with interest and penalties, can be overwhelming. Innocent spouse relief can protect you from these financial burdens.
Clear Your Name: If you’ve been unfairly tied to a tax issue you didn’t cause, the relief process can help remove you from the responsibility.
Peace of Mind: Successfully claiming relief can bring emotional relief, especially if you’ve gone through a challenging marriage.
Potential drawbacks are:
No Guarantee of Approval: The IRS does not grant relief easily. You’ll need to provide strong evidence, and the process can be lengthy and difficult.
Time Limitations: You generally must apply for relief within two years of the IRS starting collection efforts. Missing this deadline could result in losing the opportunity for relief.
Invasive Process: The IRS will closely examine your financial and personal life, including details about your marriage and finances, which could feel intrusive if you value your privacy.
Possible Strain on Relationships: If you’re still married, filing for relief could cause tension, as it might be seen as blaming your spouse for the tax issue.
Conclusion
To request innocent spouse relief, you’ll need to file Form 8857. Be prepared to provide details about the tax years involved, explain why you didn’t know about the issue, and any supporting documents (like bank statements, emails, or divorce decrees.
After submitting the form, the IRS will notify your spouse or ex-spouse, who will have a chance to respond by a specific date.
Disclaimer
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.
Here we are in yet another new year. The obligations and celebrations are over. Chances are, you’ve spent a fair amount over the holidays and might need a plan to help kickstart 2025 with some actionable financial goals. Here are a few ideas.
Create a Budget
This one never gets old. Why? It’s one of the keys to successful budgeting. You can set up a budget for the year that includes essentials, entertainment, and nice-to-haves, aka your Wish Farm. Then place it in your planner or app – there are many good ones out there. In fact, there’s a TikTok trend called loud budgeting, where people openly discuss their financial goals on social media – why they do or don’t want to buy something. If this is your thing and it helps you stay on track, go for it! If not, a good old-fashioned planner works just as well.
Bucket Your Money
This is the next step after the aforementioned. Split your money into categories: food, rent/ mortgage, utilities, medical, entertainment, vacation, etc. Apps can help you parse out these groups. You might also set up separate banking accounts for some of the necessities so you’ll know to leave them alone and not dip into them, tempting as it may be.
Set Up Auto-Drafts
Let’s say you’re saving for your child’s college fund or a down payment on a car. When you create an auto-draft for a certain amount, you’ll never miss that deposit. If you need to tweak the amount during the year, do it. Here’s the bottom line: 1) You’ll learn to live on less, and 2) you’ll be on the way to making your dreams come true.
Look for Savings Deals
Don’t just settle for the interest rate your current bank is offering. There are many options out there to grow your money. But first, do you want to lock into a fixed rate? This can be useful for long-term goals, such as buying a property. Or do you want an easy-to-access account with the ability to withdraw cash for emergencies or short-term needs like birthday or wedding gifts? Shop around.
Cancel Seldom-Used Subscriptions
Scour your bank statement. Do you need all those online magazine subscriptions? How about newsletters you pay for – the ones you rarely read? Purge your subscriptions, then see how much you’ll save. If you’re so inclined, you could put these dollars toward a gym membership. January is when all the specials appear: zero joining fees, if not a seriously cut rate.
Start a Savings Challenge
Try putting away a small amount every month. Get in the habit of emptying your pockets or coin purse. Safeguard your coins in a mason jar, and then transfer them monthly into your savings account. The next month, increase how much you contribute. Pennies, nickels, dimes, and quarters add up! After a year, you might be surprised how much you’ve saved.
Decide on Goals
These can be small or large. It’s up to you. Spend some time thinking about what’s important. Do you want to remodel your house? Contribute to a beloved charity or cause? One resource you might want to consider setting up is an emergency spending pot. This is essential and sometimes overlooked. Regardless of what you decide, figure out your parameters: how much to set aside, how often, and by when. Having financial targets gives you something to look forward to. Best of all, when you achieve your goal, it’s an awesome feeling.
More often than not, New Year’s resolutions center on getting physically fit. But if you stay the course with your finances, you’ll most definitely be, wait for it … fiscally fit!
Sources
10 things you can do right now to start 2025 with fresh finances
These articles provide general information on tax, accounting, and financial topics for small businesses and individuals. They are educational in nature and are not specific legal, accounting, financial, tax, or other professional advice, and should not be relied upon as such. This content was prepared by Service2Client and may have been reviewed or edited by the website owner for accuracy and compliance. Look for a trust mark below for verification details. No representation is made that any approach described will achieve a particular result, and no regulatory or professional body has reviewed or endorsed this content. Because each situation is different, readers should consult a qualified professional about their specific circumstances before acting. Images accompanying these articles are protected by copyright and may not be copied or reused.

 The Salt Typhoon cyberattack is among recent cyberattacks that reaffirm the urgent need for robust data security measures. This attack targeted major telecommunications providers, compromising critical infrastructure and potentially exposing vast amounts of sensitive data. With cyberthreats becoming more sophisticated, businesses and individuals must prioritize data security to maintain trust and compliance.



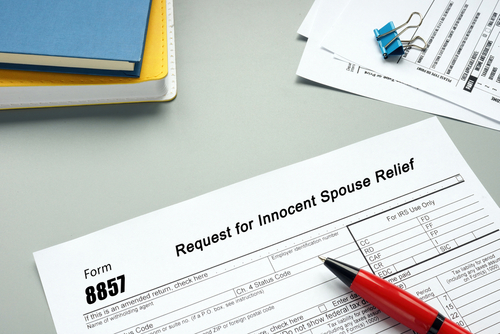 The word “innocent” in innocent spouse relief can be misleading. It doesn’t imply you’re perfect or blameless – it’s more about whether you knew or should have known about the tax issue. The IRS defines “innocence” in a specific way, and it hinges on the concept of reasonable ignorance. In short, the issue isn’t one of morality; it’s about whether you could have reasonably been unaware of a tax problem.
 Here we are in yet another new year. The obligations and celebrations are over. Chances are, you’ve spent a fair amount over the holidays and might need a plan to help kickstart 2025 with some actionable financial goals. Here are a few ideas.